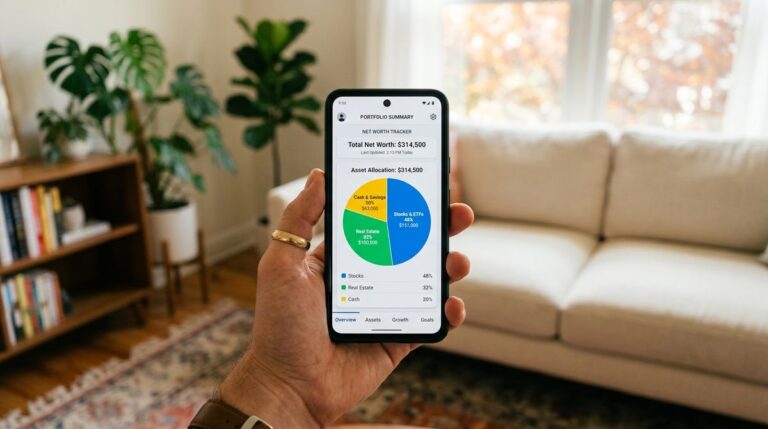
Add up what you own and what you owe once every quarter, and you will know where your money stands without guessing. A net worth snapshot is one figure built from a simple list, and it becomes more useful as the record grows. The stages below cover gathering the list, valuing each item, subtracting debts, recording the result and reading the trend. Each stage is a short task, so the whole process fits into an ordinary afternoon. This is general information for personal planning. Treat the snapshot as a personal tool rather than a report, and let it guide your own questions about saving and spending.
Listing Everything You Own
Start with bank accounts, retirement accounts, the value of a home, vehicles and any valuable personal property. Write each item on its own line with the institution or a short description beside it. Include cash on hand and balances in digital wallets that hold real money. Record each account on a separate line, even when two accounts sit at the same institution, so the list stays clear. Keep the list in one place so updates take minutes rather than hours. Add a short note beside any item that is hard to value, so the next review starts from the same assumptions. Readers may also want to visit demandquestiontime.com.
Valuing Each Item Honestly
Use the most recent statement balance for each account, and note when you checked it. Estimate the value of a vehicle using a conservative figure from a reputable guide rather than a sales advertisement. Treat personal property as a rough estimate unless you have a recent appraisal. Avoid inflating values for items you hope to sell someday. Use the same method each quarter so the trend reflects real change rather than a shift in how the items were valued. You can also visit Startup Cradles for more reading.
Subtracting What You Owe
List every debt, including mortgages, car loans, credit card balances and student loans, with the current payoff amount. Add any personal loan from a relative so the total reflects reality. Keep the payoff figure separate from the monthly payment because the two answer different questions. The payoff figure shows what you still owe in total, while the payment shows what leaves your account each month. Confirm the balances against the latest statements before you finish. Check that any loan from a relative is recorded with a clear amount and a note about whether repayment is expected. For a related read on this site, see Preparing a Basement Apartment for a Rental Listing.
Calculating and Recording the Total
Add the total of all assets, then subtract the total of all debts. Write the result at the top of the page along with the quarter it covers. A short note under the total can explain any unusual item, such as a large gift received or a one time repair bill. Record the same items in the same order every time. Keep the calculation simple enough that you can repeat it without help. A simple formula that you understand is more useful than a complex model that you rarely open.
- Keep a separate line for cash balances
- Note any large one time purchase or sale
- Save each snapshot in a labeled folder
Reading the Trend Without Overreacting
Compare this snapshot with the previous few quarters to see the direction of the total. Look for a single line that drove a big change, such as a home value shift or a loan payoff. Remember that markets rise and fall, so one quarter rarely tells the full story. Focus on whether your savings and debt paydown are moving in the right direction. Compare the direction of each category, since assets and debts can move in different ways during the same quarter. Calm reading keeps the snapshot useful. Resist the urge to compare your figures with the results of friends or public rankings, since your situation is unique.
Using the Snapshot to Set Next Steps
Choose one goal for the next quarter, such as paying down a high interest balance or building an emergency cushion. Decide which actions would move the total in that direction. Choose actions that you can control, such as a monthly transfer, rather than outcomes that depend on the market. Share the snapshot with a trusted partner if you manage money together. Check whether the goal still makes sense at the start of the next quarter. A short plan ties the numbers to real choices. Write the goal at the top of the next snapshot so you can see how well it was met when the next quarter arrives.
A Snapshot That Grows Clearer
A quarterly net worth snapshot works best when it stays simple, honest and repeatable. Each entry adds a point to a trend that shows how your finances are changing over time. The habit encourages steady attention rather than sudden reactions to headlines. Keep the list current and the method consistent, and the picture becomes easier to read. Small quarterly checks often reveal more than a single dramatic review. Over time, the record becomes a calm reference that shows steady progress and gives you confidence in your next decision.